What information is needed to review cargo insurance?
Prepare the goods type and value, packing, origin, destination and every transport stage. Read the proposed start and end of cover, exclusions and excess, then ask the insurer about ambiguities.
- 01Cargo and value
- 02Complete route
- 03Terms and exclusions
Cargo cover and carrier liability are different
Cargo insurance covers goods only within the policy terms. A carrier’s contractual liability is separate; neither automatically describes the other. Compare the declared goods, value and route with the proposed policy.
Describe the real cargo
Type and value, package count, mode, origin, destination and storage can all matter. For sensitive machinery, disclose fragility, moisture sensitivity, packing and lifting. Mention transfers and temporary storage. Incomplete descriptions can complicate both cover selection and a later claim.
Read the terms, not just the cover name
Check the insured risks, exclusions, excess, insured amount, geographic and time limits, and start and end of cover. Ask whether loading, intermediate storage and final handover are included. Obtain the policy wording or certificate applicable to this shipment before relying on a headline label.
Keep evidence before a problem occurs
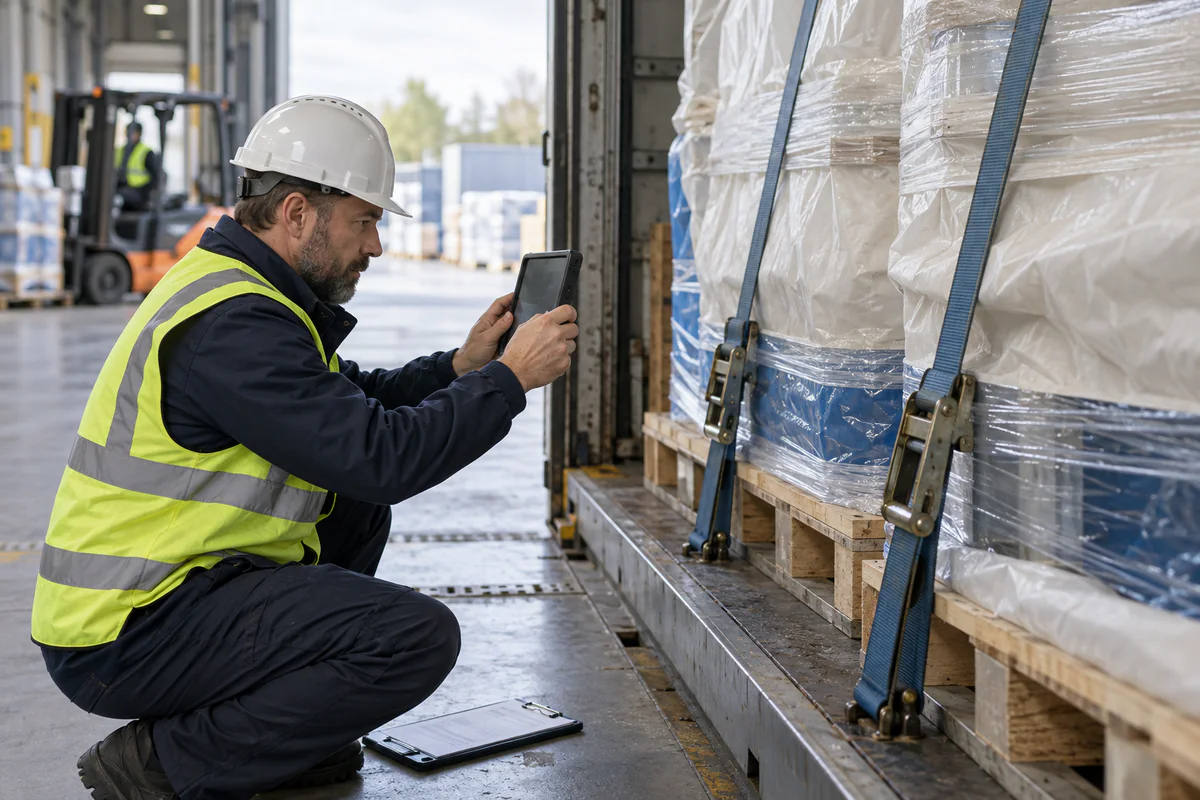
Retain invoices, packing list, pre-shipment photos, package marks, transport documents and condition reports. If damage or shortage is noticed, record it promptly and follow the notification requirements in the policy and transport contract. Good records support a review; they do not guarantee a claim payment.
Preparing cargo information for an insurance review is different from issuing a policy or handling a claim. Confirm issuance and coverage obligations with the relevant authorised insurer or intermediary.
Storage between two transport legs
Cargo waits in a warehouse after sea freight before travelling inland. Raise this stop during insurance review and ask whether the offer covers it; marine-leg cover alone does not prove cover for later storage.
Common mistakes
- Assuming full cover from a marketing label.
- Confusing carrier liability with cargo insurance.
- Failing to disclose sensitive goods or storage along the route.
Your checklist
- Describe goods, value, packages and sensitivity.
- State the full route and handling stages.
- Compare insured amount, covered risks, exclusions and excess.
- Confirm when cover starts and ends.
- Keep condition photos and documents for notification.
Questions and answers
Does cargo insurance pay every loss in a transaction?
No. Payment depends on the policy’s insured risks, limits, exclusions and the circumstances and evidence of the loss.
Does good packaging remove the need to review insurance?
No. Packaging reduces some handling risks, while the need for cover and its terms require separate assessment.
Need this reviewed for your goods?
Share the available details. Scope, timing and costs are discussed for your actual file.
Request a reviewWhat does this service include?